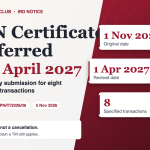

The Inland Revenue Department (IRD) has postponed the date from which a valid Taxpayer Identification Number (TIN) certificate must be submitted for eight specified transactions. The new date is 1 April 2027, not 1 November 2026. This is a deferral, not a cancellation.
In short
- IRD Notice SEC/PN/IT/2026/06, dated 5 November 2026, defers the mandatory TIN certificate requirement to 1 April 2027.
- The deferral was approved by the Ministry of Finance after heavy demand for TIN certificates, including from people outside the specified transactions.
- The legal obligation to obtain a TIN and other registration and compliance duties are not suspended.
- IRD says it will offer more convenient ways for registered taxpayers to get certificates during the extra time.
1What the notice says
An earlier IRD circular (No. SEC/PN/IT/2026/05, dated 22 September 2026) required a valid TIN certificate for eight specified transactions from 1 November 2026. The requirement rests on section 103(6) of the Inland Revenue Act, No. 24 of 2017, as amended by the Inland Revenue (Amendment) Act, No. 11 of 2026.
The IRD says it saw a large rise in requests for TIN certificates, from people who carry out the specified transactions and from others who do not. With the approval of the Ministry of Finance, it has therefore moved the mandatory date to 1 April 2027.
| Point | Position |
|---|---|
| Notice | SEC/PN/IT/2026/06, issued by the Commissioner General of Inland Revenue |
| Date of notice | 5 November 2026 |
| Original date | 1 November 2026 |
| Revised date | 1 April 2027 |
| Transactions covered | Eight specified transactions under the earlier circular (the notice does not list them) |
| Legal basis | Section 103(6), Inland Revenue Act, No. 24 of 2017, as amended by Act No. 11 of 2026 |
2What this means for you
If you plan a transaction covered by the earlier circular, you now have until 1 April 2027 before a TIN certificate becomes mandatory for it. The delay is not a general relief. You still need a TIN where the law requires one, and other registration and filing duties continue as before.
What to do now
- No TIN yet: consider registering through the IRD e-Services platform, where applicable.
- Have a TIN but no certificate: watch for IRD guidance on the alternative, more convenient ways to get a certificate.
- Planning a covered transaction: allow for the revised date of 1 April 2027 in your timetable.
- Check the circular: read the earlier circular to confirm whether your transaction is one of the eight.
3The official IRD notice
Open the notice (PDF)Original on the IRD website
If the viewer does not load on your device, use the button above to open the PDF.
This is general information, not transaction-specific tax or legal advice. Please take professional advice for your circumstances.